


Milestone
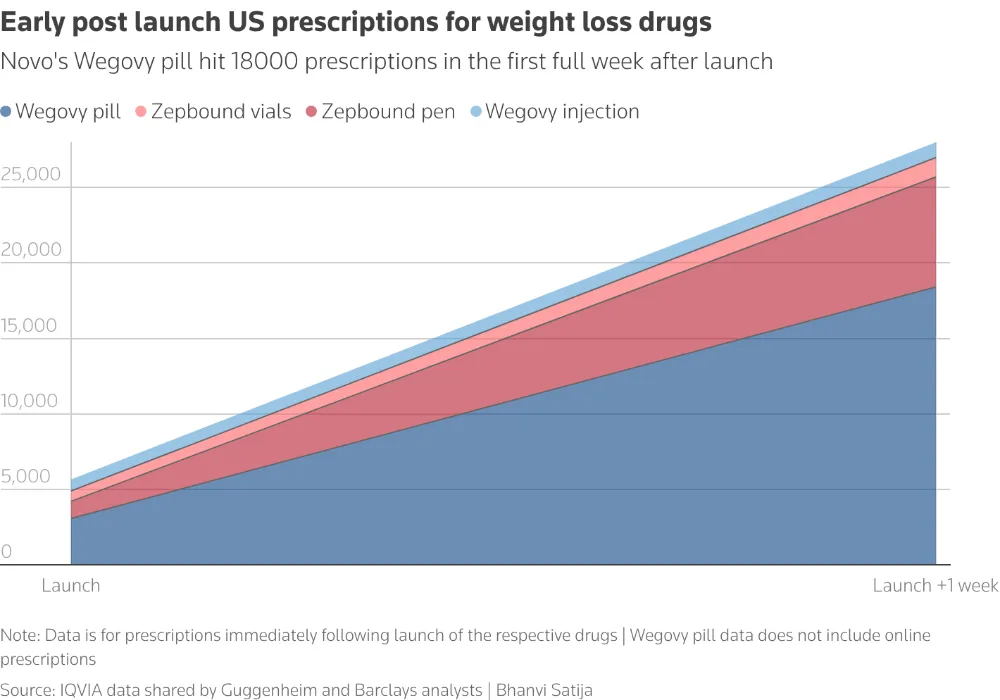
The milestone is full FDA approval and commercial launch of oral Wegovy for long-term weight management. The approval itself is notable, but the more instructive signal came immediately afterward: within two weeks of launch, the product reportedly generated about 18,400 prescriptions, with some trackers putting the number near 20,000. That is roughly twelve times the early prescription level of injectable Wegovy and about 2.7 times that of Zepbound at the same point in launch. In other words, the product did not merely enter the market. It exposed latent demand for a non-injectable obesity medicine at scale.
Disease burden and unmet need
Obesity is one of the largest chronic-disease markets in medicine, but uptake barriers remain substantial even after the success of injectable GLP-1 and GIP/GLP-1 therapies. Route of administration is one of the biggest. Many patients remain reluctant to start or persist on injectables, especially when treatment is long term and often self-paid. That makes an oral GLP-1 formulation strategically important even if it does not redefine efficacy ceilings. It enlarges the treatable population by lowering the psychological and practical threshold for initiation.
Mechanistic rationale and what is actually innovative
Oral Wegovy is still semaglutide, so the pharmacology is familiar: GLP-1 receptor agonism reduces appetite, increases satiety and slows gastric emptying. The innovation is formulation and market architecture, not first-in-class biology. That distinction matters. Oral delivery can be commercially transformative without being mechanistically novel. It allows Novo Nordisk to defend the semaglutide franchise on a new axis of competition just as obesity therapy becomes more crowded with oral small molecules, dual agonists and other differentiated programs.
Commercial evidence and pricing logic
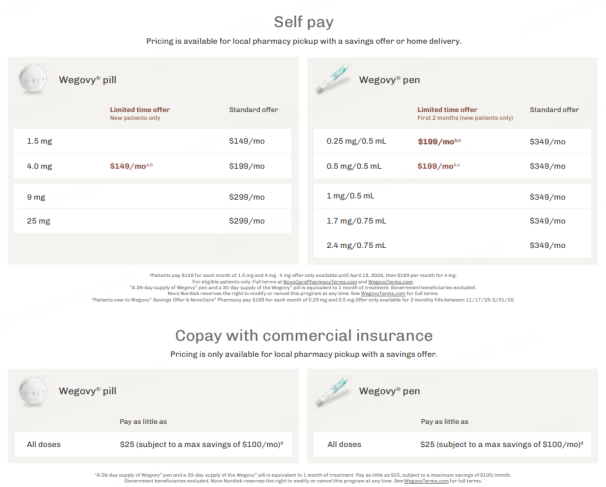
Launch economics were unusually revealing. Oral Wegovy was approved on December 22 and formally launched on January 5. IQVIA data showed 3,071 U.S. prescriptions in the first four days. List pricing was set at $149 per month for 1.5 mg, $199 for 4 mg, and $299 for 9 mg or 25 mg, while insured patients could access treatment at about $25 per month. The important point is not the exact rebate structure but the fact that Novo Nordisk deliberately created a stepped pricing ladder to drive adoption. If sales momentum holds, oral semaglutide could reach $1 billion in revenue faster than the three years it took the injectable franchise to cross that threshold.
Therapeutic positioning and competition
Oral Wegovy is unlikely to displace high-potency injectables as the efficacy benchmark in obesity. Its more realistic role is to expand the treated pool by capturing patients who want meaningful weight reduction but resist injections. That positioning still matters enormously because obesity is a scale market. A slightly less potent but easier-to-start therapy can generate outsized volume. Novo Nordisk has not won the route-of-administration race uncontested. Competitors are advancing oral obesity programs that aim for higher bioavailability, weekly dosing, small-molecule formats or dual-target mechanisms.
Safety and long-term use considerations
The discussion here centers mainly on market dynamics rather than adverse-event detail, but the relevant clinical point remains familiar. Oral semaglutide will carry the class-consistent gastrointestinal tolerability profile and the adherence questions associated with chronic metabolic therapy. For an oral product, persistence may prove especially important. A medicine that is easier to start but harder to sustain in practice would blunt the commercial case quickly.
Outlook
Oral Wegovy matters because it opens a new layer of the obesity market rather than simply extending an existing franchise. It lowers the entry barrier for many patients, gives Novo Nordisk a new commercial weapon and signals that route of administration will increasingly shape obesity competition alongside raw efficacy. The next phase will be defined by lifecycle execution: additional geographies, potential label expansion into cardiovascular risk or MASH, and defense against a coming wave of oral challengers. The launch does not settle the obesity race, but it clearly starts a new chapter in how that race will be run.

